Hard Money Loan Costs Beyond the Rate: What Milwaukee Flippers Should Check Before Signing
Hard Money Loan Costs Beyond the Rate | Milwaukee
One month of delay can cost a Milwaukee flipper more than a 2-point rate gap. See the math, the hidden fees, and what to ask before you sign.
Days on Market Are Hitting Your Profit Margin Harder
With 30-year mortgage rates back above 7%, fewer buyers can afford to buy, and the ones who do are slower to commit. Flips that sell fastest in this market are priced to current comps from day one, staged where buyers look hardest, and legally cleared before listing so nothing stalls at the closing table.
The Fine Print Problem:
Most lenders underwrite the numbers. Learn why a lender who's also a licensed real estate attorney adds value by preventing issues that sink deals.
Milwaukee’s Online Foreclosure Auction Process
Milwaukee County is changing how foreclosure properties are auctioned. If you invest in southeastern Wisconsin, this shift will affect how you plan and compete.
For years, foreclosure properties in Milwaukee County were sold at in-person sheriff's sales. Local investors know that process well. The county is moving those auctions to an online platform called Bid4Assets. When it launches, the mechanics of participating will be different.
Here is what to know before that happens.
What Makes a Renovation Project Financeable?
While important, the purchase price is the least interesting number in a renovation deal.
It tells you what someone invested as the starting point, but says nothing about whether the project can actually be funded, executed, and exited. Lenders who underwrite on purchase price alone miss the real question: does this deal hold together when something goes sideways? Borrowers who pitch on purchase price alone leave the most important arguments unmade.
Here's what actually determines whether a renovation project is financeable, and what separates the deals that close from the ones that don't.
Private Lending, Bridge Loans, and SBA: Which Tool Fits Which Deal?
Should you use private lending or go SBA?
It's one of the most common questions I get from newer investors, and it's usually the wrong question to start with. Private lending, bridge loans, and SBA financing aren't competing options you have to choose between. They're different tools built for different stages of a deal, and once you know how to use them, much of the confusion around financing goes away.
I'm Debra Hayes, attorney and owner of MGM Private Capital. I've seen good borrowers lose time and solid deals by going to the wrong lender at the wrong moment. Not because they weren't qualified, but because nobody took the time to explain how these tools actually work or how they can fit together.
Here is a plain-language guide to what each one does, when to use it, and how they work as a sequence rather than a choice.
If the Market Softens, Will You Be Ready?
The conversations happening in real estate right now have a familiar edge to them. At events, on calls, in group chats, investors and lenders are asking the same question: is the market actually softening, or is this just worry?
It's worth taking a look, because there is some data behind the fear. But there is also opportunity hiding inside it.
Here’s a look at the data, and what’s happening nationally versus locally in Southeastern Wisconsin real estate.
4 Deals Your Bank Won't Touch
You've found a great deal. The numbers are great, but your bank says no.
This is a familiar story. Wisconsin investors are creative, but conventional lenders operate inside a narrow box. They need to see seasoned income, clean collateral, and 60+ days to close.
But real estate doesn't wait.
Here are four deals that consistently fall outside that box, and why private capital is what gets them done.

From Threshing Barn to Rental Income:
From Threshing Barn to Rental Income: A Recent MGM Private Capital Deal in Mequon
Not every deal fits a standard template. This one certainly didn't, but that’s what made it a deal worth funding.

THE DEAL FINANCING PLAYBOOK
Before You Chase the Rate, Run Through This Checklist To Save Time, Holding Costs, and Frustration.
Most investors learn this the hard way. They get a great quote, spend weeks in underwriting, and watch the seller walk when closing gets pushed. The earnest money is gone. So is the deal.
Before you commit to a lender, run through this checklist.

How Tariffs Are Affecting Rehab Costs for Wisconsin Real Estate Investors in 2026
If you've priced a rehab project in 2026 and felt like the numbers looked different from what they did even a couple of months ago, you're right. They are different, and tariffs are a significant reason why.
For fix-and-flip investors and new-construction borrowers in southeastern Wisconsin, tariff-driven material cost increases are really impacting the budget.
This article breaks down the Q1 2026 Milwaukee metro housing market data by county, explains why inventory remains the defining constraint for local investors, and covers what being prepared looks like in a sub-three-month supply market.

Wisconsin Ranked #6. Here's What the Local Data Actually Shows.
Wisconsin may have ranked as the #6 hottest real estate market in the country for 2026, according to Construction Coverage, but statewide rankings only tell part of the story. For real estate investors in southeastern Wisconsin, the question that actually matters is what's happening at the county and neighborhood level, because a property in Waukesha doesn't compete the same way as one in Wauwatosa or Milwaukee's north side.
This article breaks down the Q1 2026 Milwaukee metro housing market data by county, explains why inventory remains the defining constraint for local investors, and covers what being prepared looks like in a sub-three-month supply market.

2025 Returns Are Filed. What Can Real Estate Investors Expect for 2026?
For many real estate investors, the weeks right after tax season are the best time to step back and think about strategy. You’ve just reviewed last year’s numbers, seen where profit was made, where it was lost, and where the tax treatment may have been working for you — or against you. And with the One Big Beautiful Bill now signed into law on July 4, 2025, there are meaningful changes that could affect how 2026 deals are structured.

Fix and Flip Strategies: The Deal Is the Deal.
Do You Need Strong Credit and an Appraisal to Get a Fix-and-Flip Loan?
Two investors can look at the same distressed property in Wauwatosa. One assumes he can't finance it, because his credit isn't perfect or the house won't appraise in its current condition. The other moves on it. More than almost anything else, this assumption is what keeps investors on the sidelines when they could be winning deals.
The key point is that fix-and-flip lending doesn't work like a conventional mortgage. Understanding the actual requirements can change the way you evaluate deals, and help you win more.
Fix and Flip Strategies: Protecting Your Margin From the Unexpected
Fix and Flip Strategy: Protecting Your Margin From the Unexpected
Flipping is still a great strategy, but it isn’t “easy money” anymore.
According to ATTOM’s Q3 2025 Home Flipping Report, the typical gross return on investment (ROI) for flipped homes dropped to 23.1%, down from 26.5% in the previous quarter and nearly 30% a year earlier — the lowest level seen since before the 2008 housing downturn.Source: ATTOM Data Solutions Q3 2025 Home Flipping Report.
This data reinforces something experienced investors already know: carry costs and budget overruns matter more now than they did a few years ago.
Fix and Flip Strategies: Why ARV Accuracy Leads the Way
Fix and Flip Strategies: Why ARV Accuracy Leads the Way
When investors talk about “fix and flip strategies,” the conversation usually starts with tactics: where to find deals, how to negotiate harder, how to stretch margins.
But the strongest flips don’t begin with tactics.
They begin with one number: ARV — After Repair Value.
That number determines almost every decision that follows. If it’s solid, the rest of the plan has structure. If it’s inflated, the whole deal could crumble.
What the New FinCEN Rule Means for Wisconsin Investors and Sellers
What the New FinCEN Rule Means for Wisconsin Investors and Sellers
Starting March 1, 2026, a new federal regulation from the Financial Crimes Enforcement Network (FinCEN) will change how many real estate closings are handled, especially for deals funded with hard money or private capital.
These changes aim to reduce money laundering through real estate, but for our local investors and sellers, they also bring new steps, new paperwork, and a few practical challenges to prepare for now.
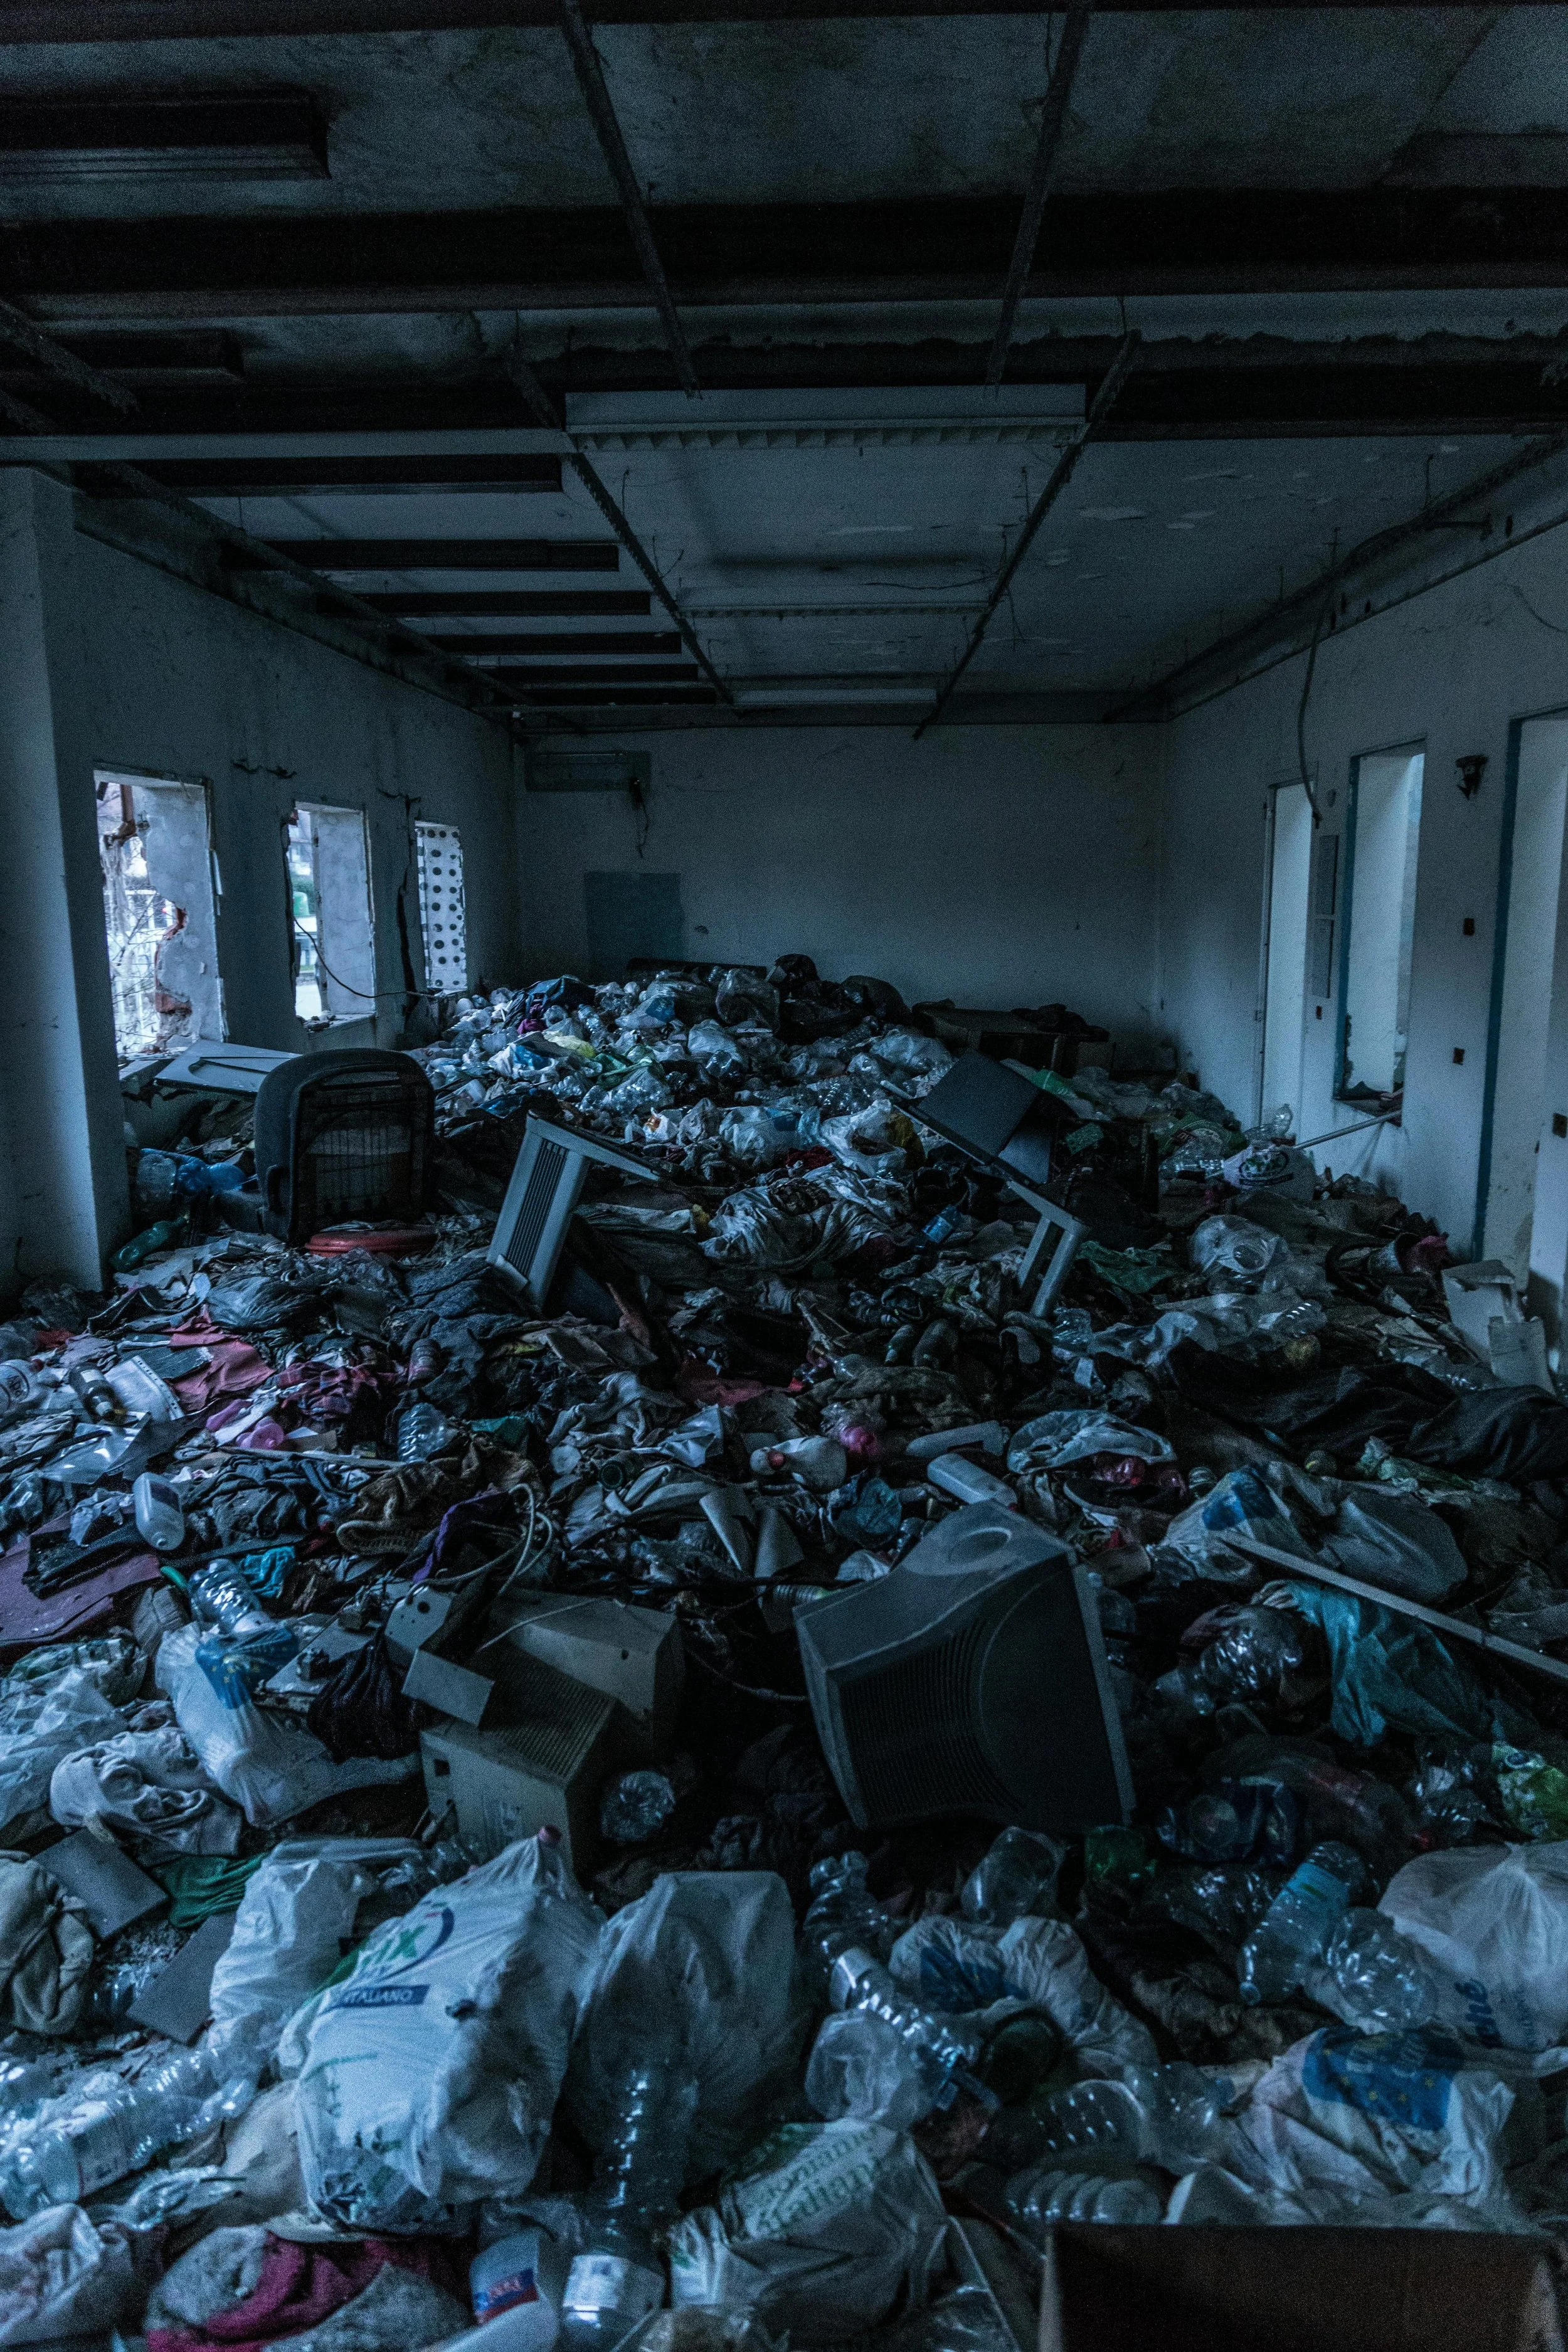
Seeing What Others Can’t
Property spotlight: investors who can see what others miss, see the trash and disrepair as an opportunity.

Going Up! How Adding a Level Can Multiply Profits
Going Up! How Adding a Level Can Multiply Profits
If you’re an experienced investor in southeastern Wisconsin, you’ve noticed the rising prices and tight inventory in premium neighborhoods. Here’s a strategy that’s delivering outsized returns: adding a second level to an existing home.
In areas where land is scarce and single-family homes already cost a premium, going up can unlock significant value—and profit—if executed well.
Why Going Up Works in Wisconsin
Land is limited, but demand is strong
Neighborhoods like Whitefish Bay, Elm Grove, Shorewood, Mount Pleasant, and parts of Wauwatosa and Brookfield have seen increasing demand for larger, modern homes. Buyers in these areas know what they want: open layouts, modern finishes, extra bathrooms, and premium features. Often, the lot size is insufficient for an addition, but buyers are willing to pay more for additional square footage.
Price per square foot escalates sharply with “premium” space

Transparency, Trust, & Terms
Transparency, Trust, and Terms: How to Pick the Right Funding Partner
If you’re a real estate investor in southeastern Wisconsin, you’ve noticed that private money is flowing, and with it, more lenders than ever are vying for your deals. On the surface, that’s good news. More choices should mean better terms, competitive rates, and improved service.
But how do you separate the lenders who truly have your best interests in mind from the ones who don’t?